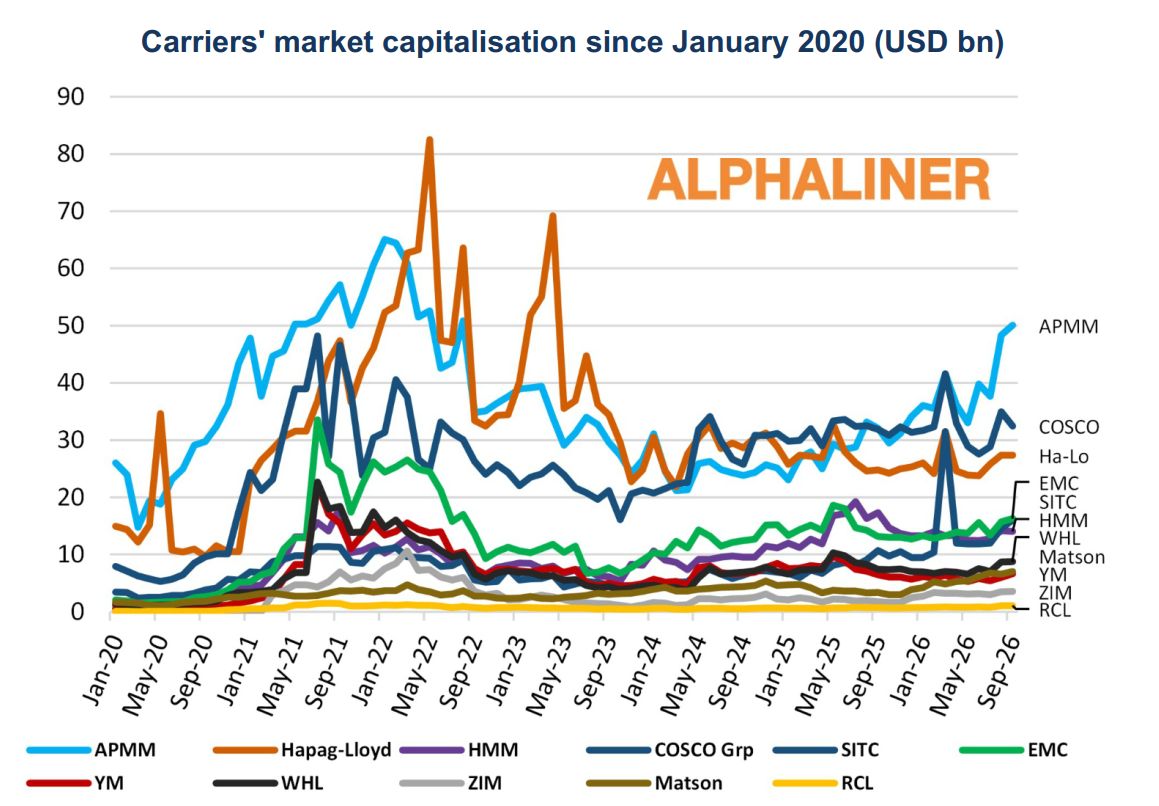
Between August and September, the share prices of most listed operators reached their highest levels in the past 12 months, driven by solid second-quarter results and the continued favourable outlook for the freight market.
According to Alphaliner’s latest market analysis, eight of eleven leading and mid-level companies reached their annual high in the weeks following the publication of their second-quarter results. The exceptions are Hapag-Lloyd, HMM and Yang Ming Marine Transport, which had already reached their peak share prices in March.
The market is being driven mainly by strong demand, ongoing geopolitical tensions and congestion at various ports – factors which are fuelling expectations that freight rates will remain firm over the next few months as well.
A.P. Moller – Maersk are among the carriers that have benefited most from this scenario. In the second quarter, the group recorded an operating profit of $935 million from its liner shipping business, whilst freight rates rose by 22% compared with the same period last year –outperforming the other major carriers.
In September, six financial institutions — HSBC, Morgan Stanley, Fearnley Securities, Citi, Goldman Sachs and Kepler Cheuvreux — raised their share prices.
HSBC and Fearnleys have also confirmed a ‘buy’ recommendation on the shares. HSBC subsequently raised its share price further, setting it at 27,000 Danish kroners.
In addition to the positive outlook for market performance for the rest of the year, analysts have recognised Maersk’s ability to capitalise particularly effectively on the rise in freight rates.
A key factor was the company’s growing exposure to the spot market: the proportion of capacity subject to spot rates rose to 56%. Added to this are the effects – as yet not quantified in detail – of the group’s investments in digital technology.
Translation by Giles Foster